Choosing a Gold Dealer
How to Invest in Gold in the UK
A UK guide to physical bullion, vaulted gold, exchange-traded products and mining shares, including costs, custody, tax, risk and exit planning.
At a glance
How can someone in the UK compare the main ways to invest in gold?
Start with financial readiness and a defined purpose. Compare physical bullion, vaulted ownership, exchange-traded products and mining shares by legal asset, custody, total cost, tax, liquidity and exit route.
- Gold produces no income, so returns depend on the sale price after all costs.
- Physical bullion, vaulted gold, listed products and mining shares create different legal rights and risks.
- Investment-gold VAT rules and Capital Gains Tax treatment depend on the exact product.
Written by
Richard Lyttle leads Bullion House across product standards, customer experience, and educational review. He reviews high-trust buying guidance so customers can understand physical gold, tax-sensitive product features, and resale considerations before they buy.
Reviewed by Liam Yarwood on 22 Jul 2026
On this page
There are several factors to consider when learning how to invest in gold in the UK, including the type of gold you buy, how you store it, and how it will be taxed. Gold has been used as a store of value for centuries, but there are several ways to gain exposure to it today.
Each approach gives you something different. Physical bullion gives you direct ownership of gold, while a listed product gives you exposure through a financial security. Mining shares give you an interest in a business rather than the metal itself. The right choice depends on why you want to invest, how long you expect to hold the investment, how much volatility you can accept, and how you want to access your money later.
When you're exploring how to invest in gold in the UK, points to keep in mind include the type of gold that suits your goals best, SIPPs, tax, costs, storage, and portfolio allocation.
Why invest in gold?
There are several benefits to investing in gold in the UK:
- Protection against inflation: Paper currencies lose their purchasing power when the cost of living soars and central banks keep printing more money. Gold is an effective long-term hedge against inflation.
- Tax advantages: Certain gold coins are exempt from Capital Gains Tax in the UK. Additionally, specific gold bars and coins are VAT-exempt, making it very cost-effective to purchase.
- Universal recognition and acceptance: When global crises, such as wars, unrest, trade tensions, and economic shutdowns occur, gold is accepted where certain currencies are not.
- Safeguard against counterparty bankruptcy risk: Buying physical investment gold has the added benefit of not being threatened by any organisation's bankruptcy.
- Portfolio diversification: Gold can help diversify a portfolio because its price doesn't always move in the same direction as shares, bonds or other assets, which may reduce reliance on the performance of any one part of an investment portfolio.
Before buying, consider what role gold is intended to play in your overall finances and how long you expect to hold it.
Choose how you want to invest in gold
Understanding how to invest in gold in the UK starts with choosing the form of gold investment that best fits your objectives, whether that's physical bullion, an exchange-traded product, mining shares or an eligible pension investment.
These options provide different forms of ownership and exposure. Physical bullion gives you a tangible asset, while an exchange-traded product gives you exposure through a financial security. Mining shares represent an investment in a company and can therefore be affected by factors beyond the gold price.
Physical gold
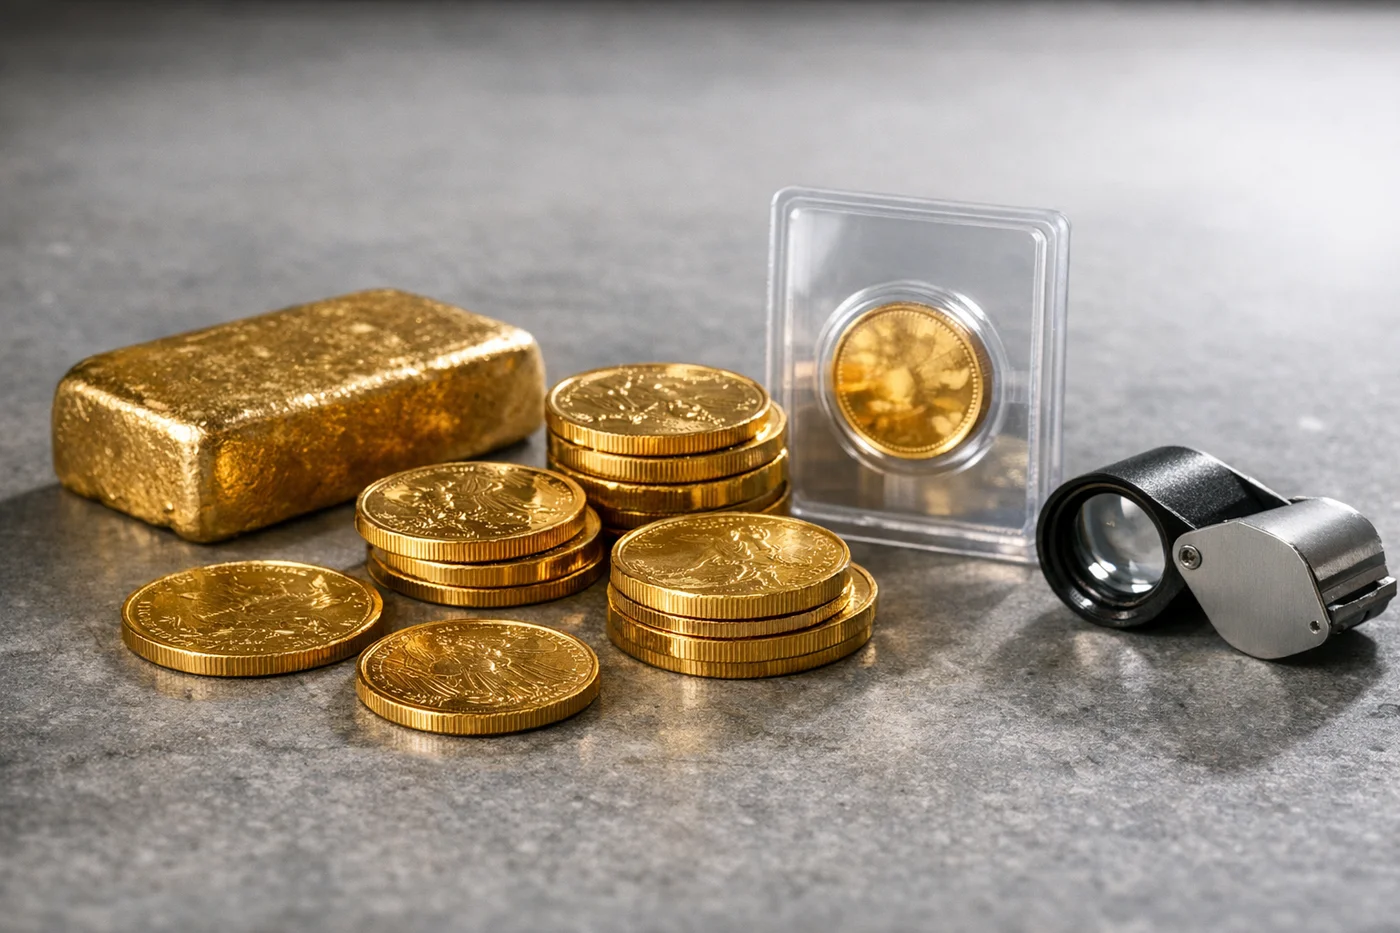
Physical gold is available mainly as coins and bars. Investment-grade bullion is valued primarily according to its fine-gold content, although its size, design, condition and market demand can affect the price.
Coins can be useful if you want to buy or sell smaller amounts over time. Bars range from small fractional sizes to larger investment bars, with larger bars often carrying lower premiums per gram.
When comparing products, look at the amount of pure gold rather than simply the gross weight.
Vaulted and allocated gold
Some services allow investors to buy gold that is held in professional storage rather than delivered to their home.
Before using a vaulted service, check:
- Whether the gold is allocated or unallocated
- Who legally owns the metal
- Where it is stored and whether it is insured
- What storage charges apply
- Whether you can request delivery
- How you can sell your holding
- What happens if the provider or custodian fails
The legal structure is important, so read the terms carefully before committing money.
Exchange-traded gold products
UK investors can also gain exposure to gold through exchange-traded securities. These can be bought and sold through a stockbroker without taking physical possession of bullion.
You may see products described as ETFs, ETCs or ETPs. Their structures can differ, so check the terms carefully. Consider the product's fees, issuer, custodian, and ability to track the gold price.
An exchange-traded product can suit investors who want gold-price exposure without storing physical bullion, but it shouldn't be treated as identical to owning a gold coin or bar.
Gold-mining shares
Buying shares in a gold-mining company gives you exposure to a business rather than direct ownership of gold.
A mining company's share price can be affected by the gold price, but also by production costs, energy prices, mine quality, political conditions, debt, and management decisions.
Mining shares may suit investors seeking exposure to the gold industry, but they aren't a substitute for physical bullion if your objective is direct gold ownership.
Physical gold or paper gold?
The distinction between physical and paper gold is important before you invest.
With physical gold, you own a coin or bar. Costs can include the purchase premium, delivery, insurance and storage, while selling involves finding a buyer and accepting the prevailing buy price.
With an exchange-traded product, you hold a security through a broker or investment platform. You avoid the practical requirements of storing bullion but have dealing costs, product charges and risks associated with the provider and structure.
- Option
- Gold coins
- What you own
- Physical bullion
- Main costs or risks
- Premium, storage, insurance, and resale spread
- Option
- Gold bars
- What you own
- Physical bullion
- Main costs or risks
- Premium, storage, insurance, and resale spread
- Option
- Vaulted gold
- What you own
- Allocated or contractual interest
- Main costs or risks
- Storage, provider and custody arrangements
- Option
- Gold ETC/ETP
- What you own
- Listed security
- Main costs or risks
- Product charges, dealing costs, and issuer structure
- Option
- Gold-mining shares
- What you own
- Company shares
- Main costs or risks
- Business, market and company-specific risks
| Option | What you own | Main costs or risks |
|---|---|---|
| Gold coins | Physical bullion | Premium, storage, insurance, and resale spread |
| Gold bars | Physical bullion | Premium, storage, insurance, and resale spread |
| Vaulted gold | Allocated or contractual interest | Storage, provider and custody arrangements |
| Gold ETC/ETP | Listed security | Product charges, dealing costs, and issuer structure |
| Gold-mining shares | Company shares | Business, market and company-specific risks |
The choice depends on your preferred form of ownership, costs, liquidity and investment objectives.
How much gold should you have in your portfolio?
There is no single percentage that suits every investor.
Your allocation depends on factors including your income, emergency savings, debts, existing investments, pension arrangements, investment timeframe, and tolerance for losses.
Rather than following a fixed percentage, consider what you want gold to achieve and how much you could afford to hold without having to sell at an inconvenient time.
If you want personal advice about portfolio allocation, a regulated financial adviser can assess your circumstances and existing investments.
Lump sum or regular purchases?
A lump-sum purchase puts your intended investment into gold at the prevailing price. Regular purchases spread buying across different dates, reducing reliance on a single purchase price but not guaranteeing a better overall result.
Multiple purchases can also mean paying premiums, delivery charges or dealing costs more than once.
Whichever approach you choose, establish your investment objective before you start buying rather than changing your strategy in response to short-term price movements.
Gold and your SIPP
A Self-Invested Personal Pension (SIPP) gives the member greater control over the investments held within the pension, subject to the scheme's rules and applicable legislation.
Some pension arrangements can hold investment-grade gold bullion. HMRC has the following rules for physical gold investment in SIPPs:
- Bars and wafers must have a purity of at least 995 parts per thousand, be produced by a refinery listed on the LBMA, and be of a weight accepted by the bullion markets.
- Gold coins must be approved by the HMRC list of investment-grade coins.
- The gold must be stored in an approved, insured vault. Members may not store the bullion privately.
- The gold must undergo an independent valuation at the current market rates.
How it works
Your SIPP provider will typically work with a bullion dealer when investing in physical gold on your behalf. They will source the products, move them to a secure, insured vault, and produce a statement showing the gold at its current market value. When you sell, the cash is returned to the SIPP.
The most significant advantage of investing in gold through a SIPP is the tax relief on contributions, which ranges from 20% to 45%. HMRC limits this investment to the lower of your annual income and £60,000.
HMRC states that gains arising from investments held for the purposes of a registered pension scheme are exempt from Capital Gains Tax. Investment income and gains within registered pension schemes are generally subject to their own pension tax treatment.
Pension tax treatment doesn't make an investment risk-free. Pension money is intended for retirement, access is restricted by pension rules, and the scheme will have its own charges and conditions.
If you're considering gold within a SIPP, compare the cost and structure of the pension arrangement as well as the gold itself.
Understand the UK tax position
Tax treatment is an important consideration when choosing between different forms of gold.
VAT on investment gold
Qualifying investment gold is generally exempt from VAT under HMRC rules. For gold coins, HMRC applies specific criteria relating to purity, legal-tender status and normal selling price.
The exemption doesn't apply automatically to every gold product, so check the exact coin or bar before buying.
Capital Gains Tax on gold
There is no blanket Capital Gains Tax exemption for physical gold.
Qualifying Sovereigns and Britannia gold coins are treated as sterling currency and are exempt from CGT under the relevant legislation. This treatment doesn't automatically apply to other gold coins. HMRC identifies non-sterling coins such as Krugerrands as chargeable assets.
Gold bars and other chargeable gold investments can therefore create a taxable capital gain when sold.
For the 2026/27 tax year, the annual CGT exempt amount is £3,000. Where CGT is payable, the applicable rate depends on the taxpayer's circumstances. GOV.UK currently gives rates of 18% - 24% for gains made from 6 April 2026.
Keep purchase invoices and sale records so you have evidence of acquisition costs and disposal proceeds. For substantial holdings or unusual transactions, professional tax advice is sensible.
Choose the right gold products
Once you've decided that physical gold is appropriate, the next decision is what to purchase.
Bullion House offers a range of gold products, and our skilled team can assist you in deciding between gold coins and gold bars.
Gold coins
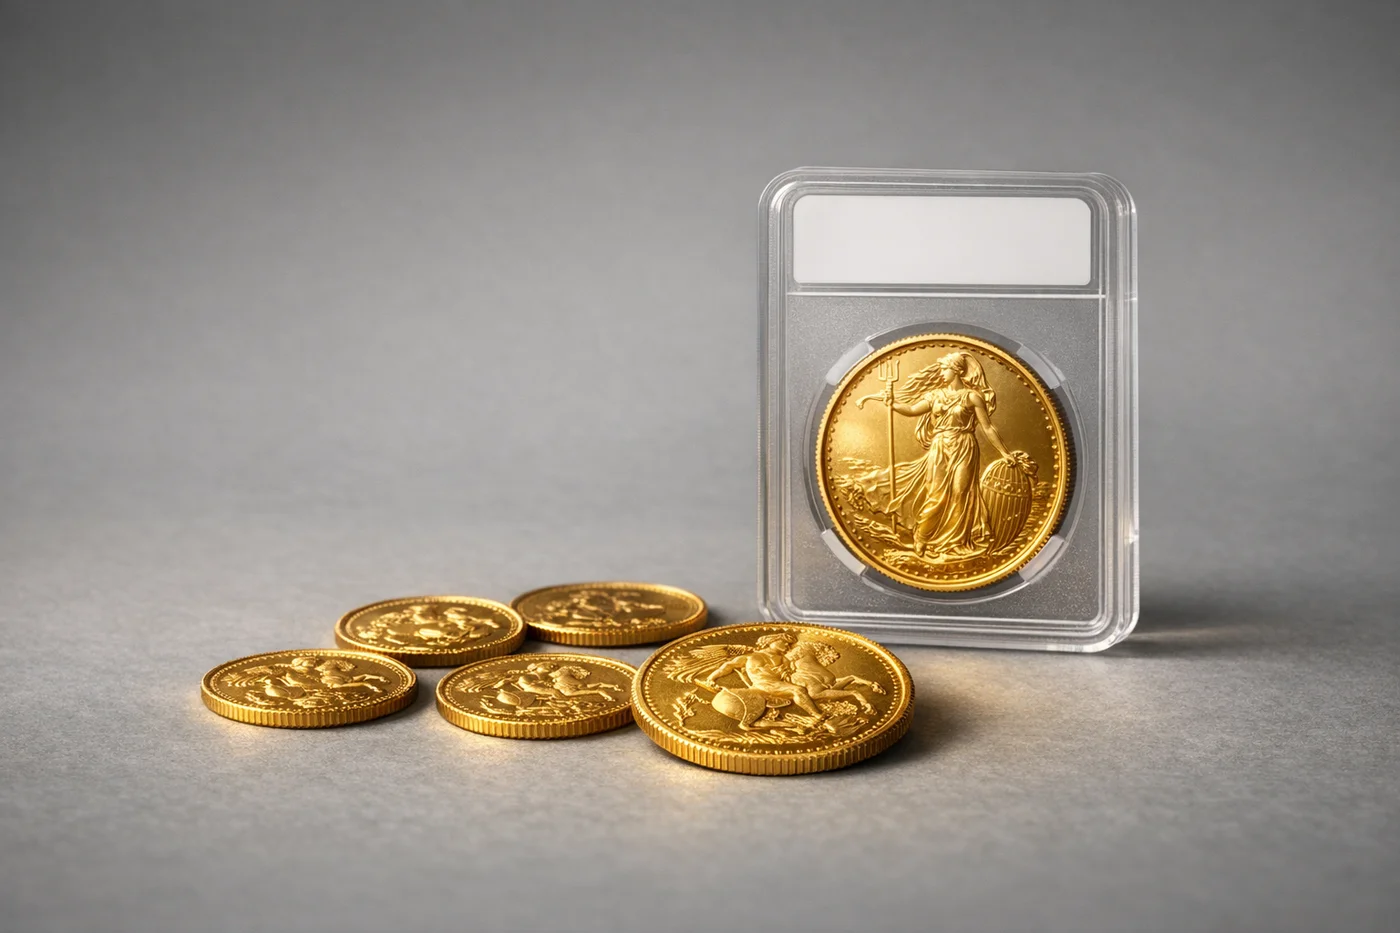
Gold coins are available in different sizes, designs, and purities. Popular investment coins include the British Sovereign and Britannia, South Africa's Krugerrand and Canada's Maple Leaf.
Coins can offer flexibility because you can sell individual pieces rather than disposing of a larger bar.
For UK investors, the tax treatment of certain British gold coins is also an important consideration. Qualifying Sovereigns and Britannias have the sterling currency CGT exemption described above.
Gold bars
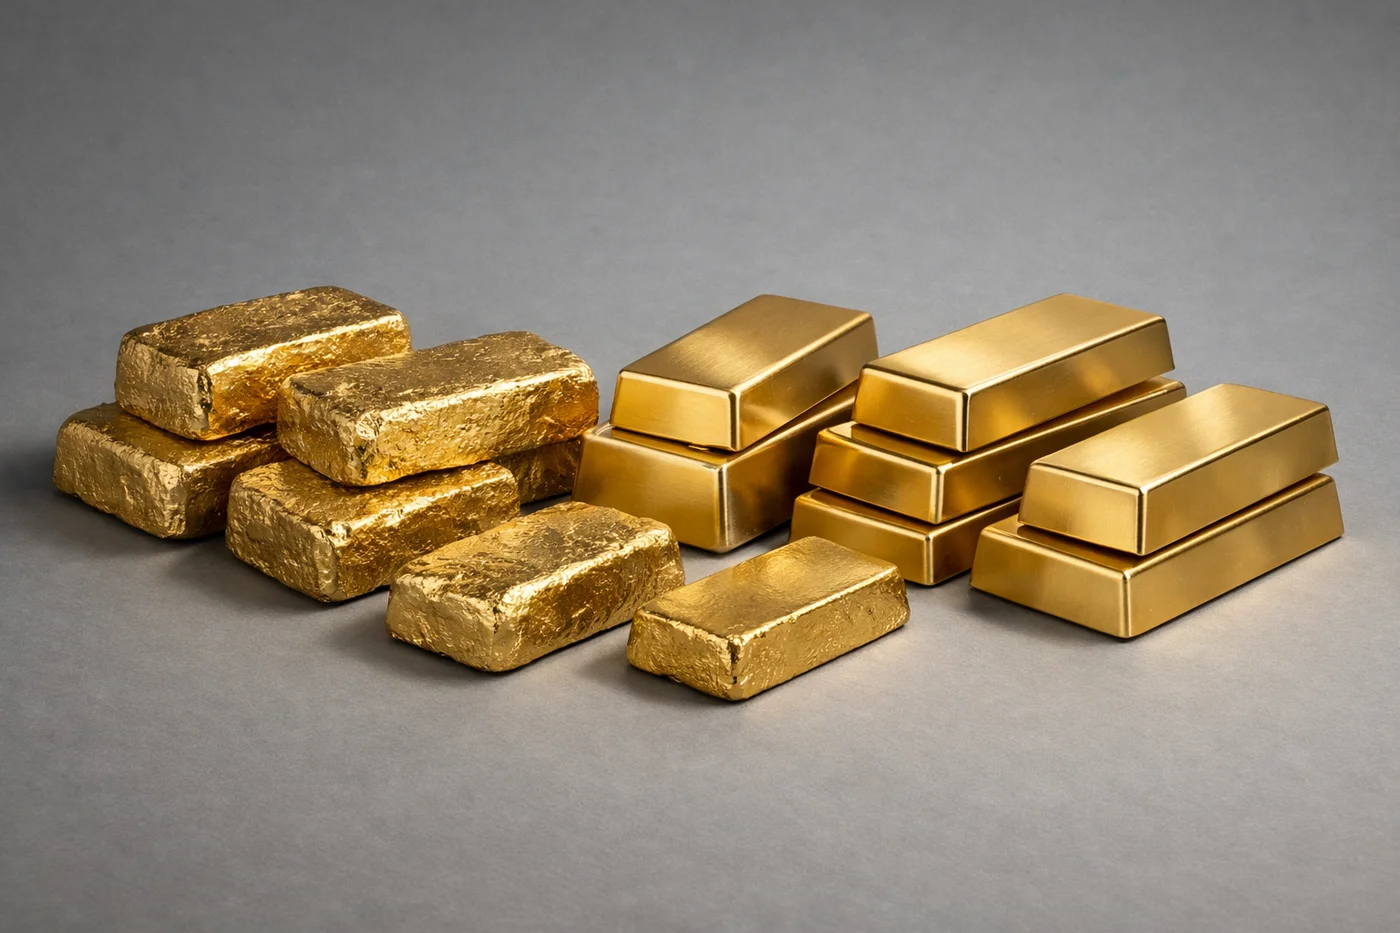
Gold bars are available in a wide range of weights. Smaller bars can make gold accessible at lower individual purchase prices, while larger bars can offer lower premiums per gram.
The trade-off is flexibility. A single large bar may be less convenient to sell in portions than several smaller bars or coins.
When comparing bars, look at the refiner or manufacturer, fineness, weight, price above the underlying gold value, and resale arrangements.
Compare the total cost, not just the gold price
The spot price shows the market value of gold, but it isn't necessarily the price you'll pay for physical bullion.
A coin or bar normally trades above its equivalent fine-gold value. This difference is the premium. Your total cost may also include delivery, insurance, storage, payment charges, and selling spreads.
Smaller products can carry higher premiums per gram because production and distribution costs are spread across less gold.
Also check the potential resale price. The difference between your purchase price and a dealer's buy-back price is an important part of the real cost of owning physical gold.
Storage and security
Physical gold needs secure storage. Some investors use a home safe, while others use a professional precious-metals vault.
Home storage gives you direct access but requires careful consideration of security, privacy and insurance. Professional storage can reduce these concerns but involves an ongoing charge.
Check insurance terms, maximum covered values and any conditions for making a claim. Keep purchase invoices and other documentation securely.
Plan how you will sell your gold
Before purchasing, consider how the product can be sold and what price you might receive.
Ask:
- Who is likely to buy the gold?
- What price do they use?
- Are there selling fees?
- How quickly will payment be made?
- Does the product need to remain in its original packaging?
- Will you need proof of purchase or identification?
Bullion House provides a Buy-Back commitment for eligible products, but check the terms applying to the particular item you are considering.
A clear exit route can make it easier to judge whether a product is suitable before you buy it.
How to choose a gold dealer
Buying from a reputable dealer is essential, particularly when purchasing high-value physical assets. Look for clear information about the business, its products, pricing, delivery arrangements and selling process.
Before placing an online order, check that you're dealing with the genuine company website and that contact details are consistent across the business's official channels. A professional-looking website isn't, on its own, proof that a dealer is legitimate.
Compare the actual product price rather than relying solely on promotional claims. Check the gold weight, purity, manufacturer or mint, delivery arrangements, and return terms.
You should also understand who you're paying and who is responsible for the bullion before it reaches you.
Build a long-term gold investment plan
A clear plan is an important part of understanding how to invest in gold in the UK, particularly when deciding how much to invest, how long to hold your gold and when you might sell.
Gold is generally best considered as part of a wider financial plan rather than as a standalone strategy. Decide why you're buying it, how much you can afford to commit and how long you expect to hold it. Consider where you'll store the gold and what circumstances would lead you to sell. Keep records of purchases, costs and valuations, particularly where CGT may apply.
If your financial circumstances change, reassess your overall allocation rather than focusing on gold in isolation. A regulated financial adviser or qualified tax professional can provide personal advice where needed.
Invest in gold with a clear plan
Gold can be held in several different ways, from physical Sovereigns and bullion bars to exchange-traded securities and certain pension investments. The important differences are ownership, risk, cost, tax treatment, liquidity, and access.
For physical gold, compare the fine-gold content, premium, storage arrangements, and resale process before buying. Pay particular attention to the CGT treatment of the specific product if you're investing outside a pension.
Tax rules and investment products can change. Check current HMRC guidance and seek regulated financial or tax advice where your circumstances require it.
If physical bullion suits your objectives, explore the Bullion House gold range, or for personal assistance, contact our experienced team.
Frequently asked questions
How can I invest in gold in the UK?
You can invest through physical gold coins and bars, vaulted gold, exchange-traded gold products, gold-mining shares and, where permitted, certain pension arrangements. Each gives you different rights, costs and risks.
Can I lose money investing in gold?
Yes. The gold price can fall, and gold doesn't generate interest or dividends. Physical gold also involves purchase premiums, storage costs and the difference between dealer buying and selling prices.
Should I buy gold coins, bars or an exchange-traded product?
Coins and bars give you physical ownership when the title is clear. An exchange-traded product gives you exposure through a listed security. Consider your objectives, preferred form of ownership, costs, storage requirements, liquidity and tax position before choosing.
Do I pay VAT when I buy gold in the UK?
Qualifying investment gold is generally exempt from VAT under HMRC rules. However, not every gold product qualifies, so check the exact coin or bar rather than assuming that all gold is VAT-free.
Is physical gold exempt from Capital Gains Tax?
Not in every case. HMRC confirms that qualifying Sovereigns and Britannia gold coins are treated as sterling currency and are exempt from CGT. Other physical gold, including many foreign coins and gold bars, can be subject to CGT.
Can I hold gold in a SIPP?
Some SIPP arrangements can hold qualifying investment-grade gold bullion, but individual providers have their own rules about permitted investments. HMRC defines investment-grade gold for pension purposes as bullion of at least 995 fineness in bar or wafer form and of a weight accepted by the bullion markets.
Is gold a good investment for retirement?
Gold can form part of a retirement portfolio, but whether it is appropriate depends on the individual's wider circumstances, existing pension investments, timeframe and tolerance for loss. A regulated financial adviser can provide personal advice on pension allocation.
How much gold should I buy?
There is no universal allocation that suits every investor. Consider your overall assets, income, cash reserves, debts, investment timeframe and ability to tolerate a fall in value. A regulated adviser can help if you need a personalised allocation.
Next practical step
Sources and further reading
Rules and market terms can change. Check the dated sources below and take advice on tax, regulation or personal finances where your position calls for it. For the practical side of buying or selling physical gold, speak to the Bullion House team.
View 18 sources
- MoneyHelper: Understand investment risk
- MoneyHelper: A beginner's guide to investing
- MoneyHelper: Save or invest
- FCA: Check a firm or individual
- FCA: Firm Checker
- FCA: Online trading scams
- FCA: High-risk investments from unregulated firms
- FCA: Safe custody services
- FSCS: Guide to investment protection
- HMRC: Gold and VAT Notice 701/21
- HMRC: Investment gold coins and VAT Notice 701/21A
- HMRC: Capital Gains Manual on gold coins
- GOV.UK: Capital Gains Tax
- GOV.UK: How ISAs work
- London Stock Exchange: Exchange Traded Commodities
- LBMA: Precious-metal prices
- LBMA: Good Delivery
- The Royal Mint: Bullion coins and bars
Related guides
Use these to check the next part of your decision.
- How to Buy Gold
Gold 101: A Beginner’s Guide to Physical Gold
Learn how physical gold ownership, coins, bars, pricing, UK tax, storage and resale work before you make a first purchase.
Read guide - How to Buy Gold
Physical Gold vs Gold ETF in the UK: ETF or ETC?
Compare physical gold with UK-listed gold ETFs and ETCs by ownership, backing, fees, tracking, custody, liquidity, ISA access, tax and protection.
Read guide