Gold and UK Tax
CGT-Free Gold in the UK
A source-led UK guide to investment-gold VAT, sterling legal-tender coins, Capital Gains Tax, non-exempt gold, records and disposal planning.
At a glance
Which physical gold products receive VAT or Capital Gains Tax exemptions in the UK?
Qualifying investment gold can receive VAT exemption. HMRC treats certain sterling legal-tender coins, including modern Sovereigns and gold Britannias, as exempt currency for Capital Gains Tax.
- VAT and Capital Gains Tax use separate rules and answer different questions.
- Qualifying bars and foreign coins can receive investment-gold VAT treatment without sterling-currency CGT treatment.
- HMRC names Sovereigns minted from 1837 and gold Britannias as sterling currency.
Written by
Richard Lyttle leads Bullion House across product standards, customer experience, and educational review. He reviews high-trust buying guidance so customers can understand physical gold, tax-sensitive product features, and resale considerations before they buy.
Reviewed by Liam Yarwood on 22 Jul 2026
On this page
Understanding which gold is CGT-free in the UK can significantly affect your profit margin when you compare coins, bars, and other physical gold. The key distinction is between VAT treatment and Capital Gains Tax treatment; they are separate rules, and a gold product can qualify for one without qualifying for the other.
For UK investors, certain sterling legal-tender gold coins receive particularly favourable Capital Gains Tax treatment. HMRC identifies Sovereigns minted from 1837 onwards and Gold Britannias as sterling currency, so they fall within the sterling currency exemption under the CGT rules.
Gold bars and many foreign bullion coins are different. A bar can qualify as investment gold and therefore be exempt from VAT when you buy it, while a later gain on its sale can still be subject to CGT.
The basics of CGT-free gold in the UK
- Qualifying investment gold can receive VAT-exempt treatment when it meets HMRC's conditions.
- Certain sterling legal-tender gold coins can receive CGT treatment as currency.
- Gold Sovereigns minted from 1837 onwards, and gold Britannias are examples HMRC identifies as sterling currency.
- Gold bars can qualify for investment-gold VAT treatment but are not sterling currency.
- Foreign bullion coins, including Krugerrands, can receive investment-gold VAT treatment while remaining chargeable assets for CGT.
- The exact product, date, issuer, denomination, and legal status matter.
- The 2026/27 annual exempt amount for individuals is £3,000.
- Main CGT rates for individuals are 18% and 24%, depending on how the gain interacts with your taxable income.
Which gold is CGT-free in the UK?
When considering CGT-free gold in the UK, the key point is not whether a product contains gold or is described as investment gold; it's its legal status.
- Gold Sovereigns minted in 1837 or later are treated by HMRC as sterling currency and receive the sterling-currency CGT exemption.
- HMRC treats Gold Britannias as sterling currency and applies the same exemption.
- Gold bars are not sterling currency and can create a chargeable gain when you sell them.
- Foreign bullion coins, including Krugerrands, can also be chargeable assets even when they are legal tender in their country of issue.
- Since VAT exemption and CGT exemption are separate, a product can qualify for VAT-free investment-gold treatment without being CGT-free.
- The tax treatment applies to the asset and the relevant transaction. Your wider circumstances can affect the calculation.
VAT vs CGT on investment gold
VAT exemption does not mean CGT exemption. VAT concerns the supply of goods or services. CGT concerns gains made when you dispose of chargeable assets. This distinction is important because a product can receive VAT-exempt treatment when you buy it but still create a taxable gain when you sell it.
Investment-gold VAT
HMRC defines investment gold through objective conditions covering the product's form, purity and market characteristics. A qualifying gold bar or wafer generally needs:
- Gold purity of at least 995 parts per thousand.
- A weight accepted by the bullion market.
- A form that meets the relevant HMRC conditions.
Qualifying gold coins must meet separate conditions. These can include purity, legal-tender status in the country of issue, date of production and the relationship between the coin's normal selling price and its gold value.
The coin does not have to be sterling legal tender to receive investment-gold VAT treatment; a foreign coin can qualify under the VAT rules even though it does not receive the UK sterling-currency treatment for CGT.
The term "investment gold" does not establish the legal treatment. Check the exact product, the current HMRC guidance and the invoice issued for your purchase. Jewellery, medals, replicas and low-purity items do not become investment gold simply because they contain gold. Product form and transaction details determine the VAT position.
Capital Gains Tax on gold
CGT applies to gains on chargeable assets. The calculation usually begins with the disposal proceeds and deducts the acquisition cost and allowable incidental costs. The following can affect the result:
- The asset's legal classification.
- The original purchase price.
- Allowable buying and selling costs.
- Losses from other disposals.
- The annual exempt amount.
- Your taxable income and applicable CGT rate.
- Whether you received the asset by gift or inheritance.
At Bullion House, we recommend checking the exact product specification and keeping your purchase invoice. The description, weight, fineness and tax treatment recorded at the time of purchase can become useful evidence later.
A qualifying gold bar may be supplied without VAT but still be a chargeable asset for CGT purposes when you dispose of it. However, a sale is not the only possible disposal. Gifts and transfers can also require analysis, particularly where connected parties or market-value rules apply.
What does legal tender mean?
Legal-tender status is central to the UK's CGT treatment of certain gold coins. A coin's face value does not, by itself, prove that the coin remains UK legal tender. You should identify the issuing authority, denomination and legal basis for the exact coin.
For less familiar products, Bullion House recommends that you retain an official specification, mint record or other reliable evidence. A marketing description or a British-themed design provides weaker evidence than the issuing authority's documentation.
HMRC treats coins as currency when they remain legal tender at acquisition or disposal. Sterling currency then receives the treatment described in section 21 of the Taxation of Chargeable Gains Act.
Which gold coins are CGT-free?
CGT-free gold in the UK usually refers to qualifying sterling legal-tender gold coins rather than all physical gold.
Gold Sovereigns
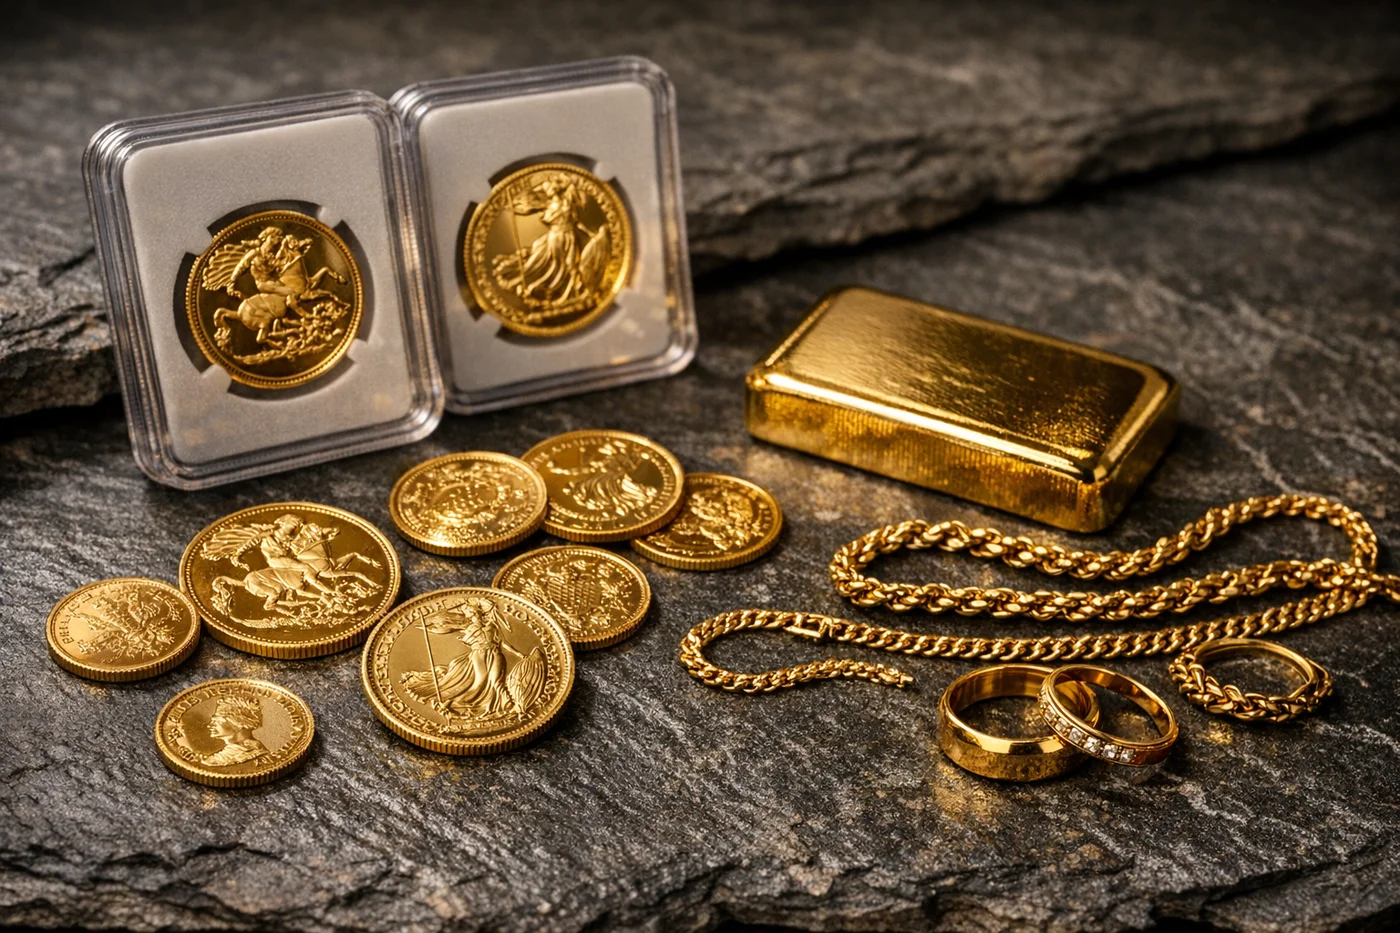
HMRC identifies Sovereigns minted from 1837 onwards as sterling currency for the purposes of its CGT guidance. A Sovereign is a British £1 gold coin, traditionally struck in 22-carat gold. A full Sovereign contains approximately 7.32g of fine gold within a gross weight of about 7.98g.
The date remains important when considering tax treatment. Earlier Sovereigns require separate analysis rather than being automatically treated in the same way.
The Sovereign family also includes different sizes and special issues. Half Sovereigns, Double Sovereigns and Five-Sovereign pieces are not simply interchangeable with a standard full Sovereign for identification purposes.
View our gold Sovereign collection
Browse full and fractional Sovereigns with specifications listed for every coin.
Gold Britannia
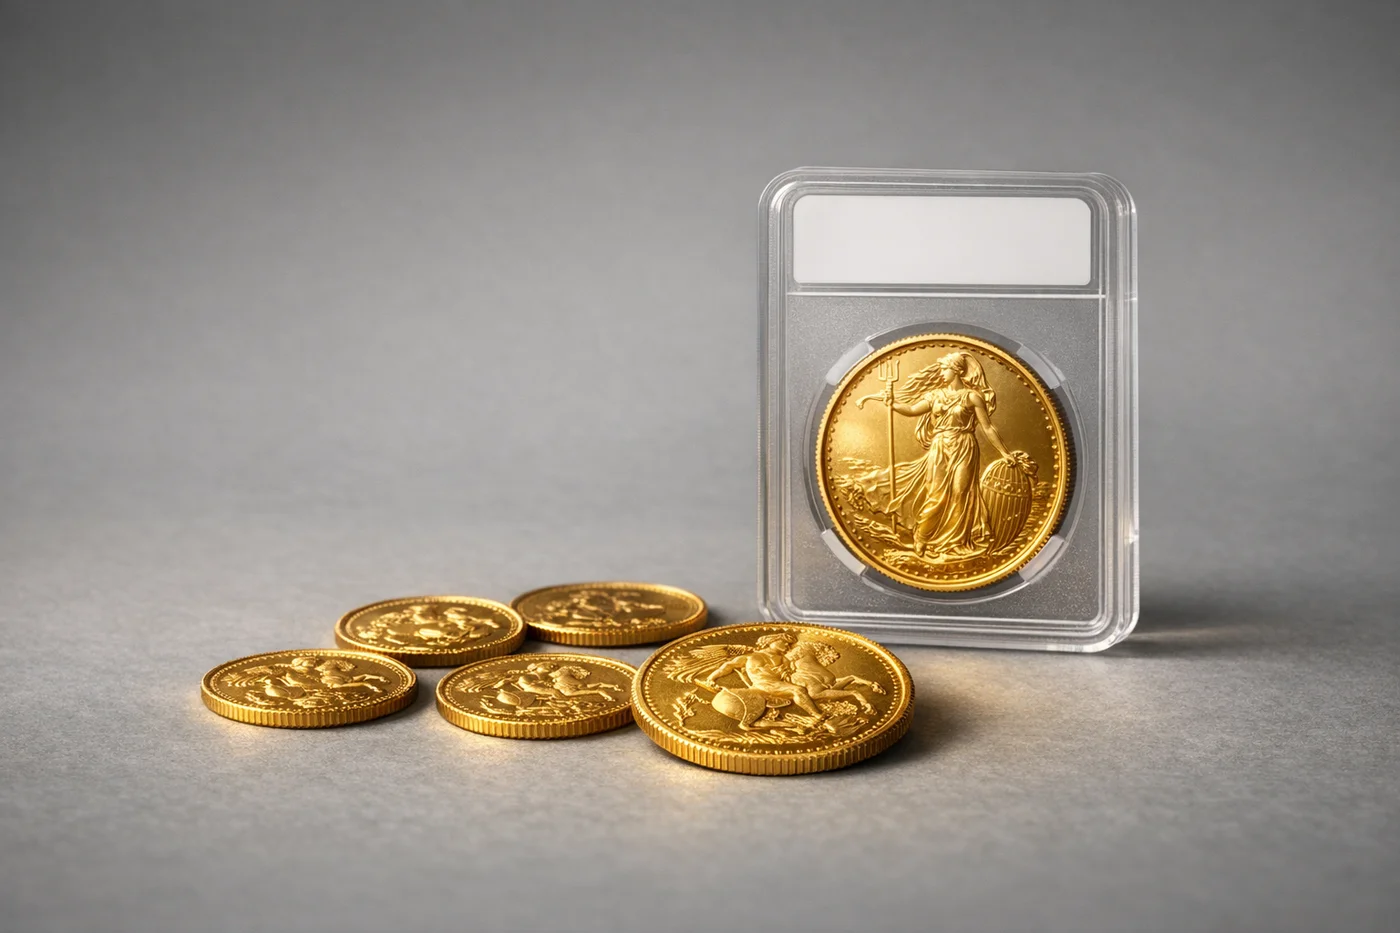
Gold Britannias are another important form of CGT-free gold in the UK. HMRC treats Britannia gold coins as sterling currency for CGT purposes. The exemption therefore applies because of their legal-tender status, not necessarily because they are British-made gold coins.
The Britannia series has changed over time. For example, modern one-ounce Gold Britannias contain one troy ounce of fine gold and use 999.9 fine gold, while earlier Britannias used a 22-carat specification. Check the exact denomination, issuing authority, year, metal and fineness before relying on the exemption.
View our gold Britannia selection
Compare one-ounce and fractional Britannias, with fineness and year shown for each coin.
Other UK legal-tender coins
The Royal Mint states that its UK legal-tender bullion coins receive CGT exemption for UK residents. However, HMRC's published manual gives named examples rather than a complete retail catalogue. This means a coin may carry a British design, Royal Mint packaging or a denomination without falling within the same treatment.
Before relying on a coin's CGT status, verify:
- The issuing authority.
- The denomination.
- Whether it remains legal tender.
- The exact metal and fineness.
- The issue date and format.
- The current HMRC treatment.
Bars, foreign coins and collector pieces
Gold bars, foreign coins and collector pieces may be eligible for VAT exemption, but are typically not CGT-exempt.
Gold bars
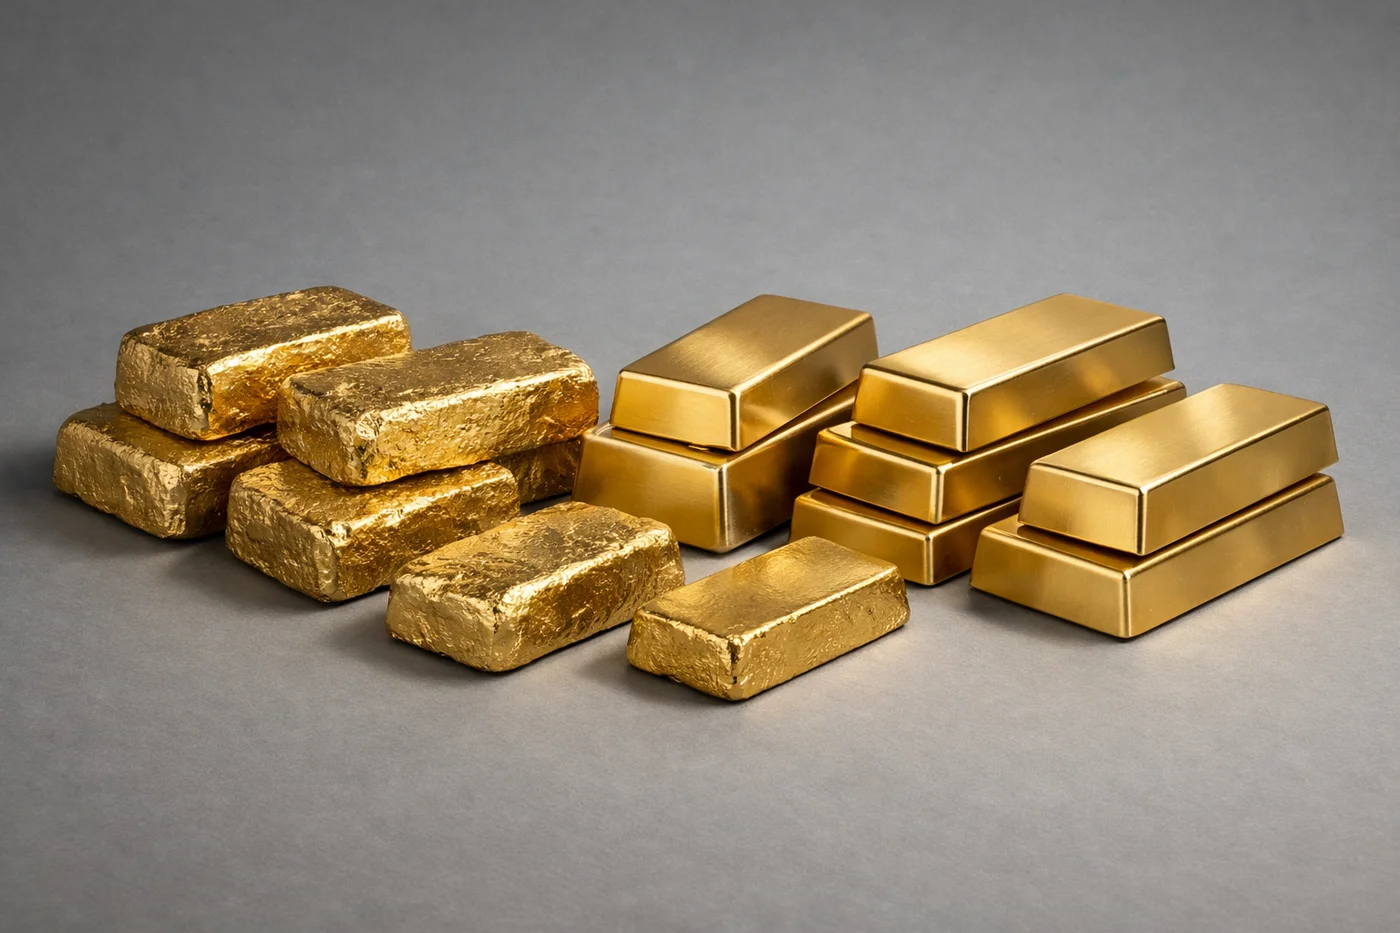
Gold bars are not sterling currency. A qualifying bar can receive investment-gold VAT exemption, but its disposal can still create a chargeable gain. This is one of the most important distinctions when comparing bars with CGT-free gold UK coins.
For example, suppose you buy a qualifying gold bar for £20,000 and later sell it for £25,000. Before considering allowable costs, losses and exemptions, the gain is £5,000. The bar's VAT treatment at purchase does not remove the CGT calculation.
Bars can still offer practical advantages. Larger bars may carry a lower percentage premium than smaller products, although the best choice depends on your budget, storage arrangements, liquidity and planned selling size.
Browse our gold bar range
Compare cast and minted bars by weight, refiner and fineness.
Foreign bullion coins
HMRC uses Krugerrands as an example of foreign currency that is a chargeable asset; Krugerrands can still qualify for investment-gold VAT treatment under separate rules.
Other foreign bullion coins require product-level review. A Maple Leaf, Philharmonic or American Eagle may satisfy investment-gold VAT conditions while remaining outside the sterling-currency treatment for CGT.
At Bullion House, we advise that you do not assume that a coin is CGT-exempt because it:
- Is issued by a national mint.
- Has a face value.
- Is legal tender in its country of origin.
- Contains one troy ounce of gold.
- Appears on an investment-gold VAT list.
View all gold coins
See every gold coin we stock, with specifications and current pricing.
Collector coins and sets
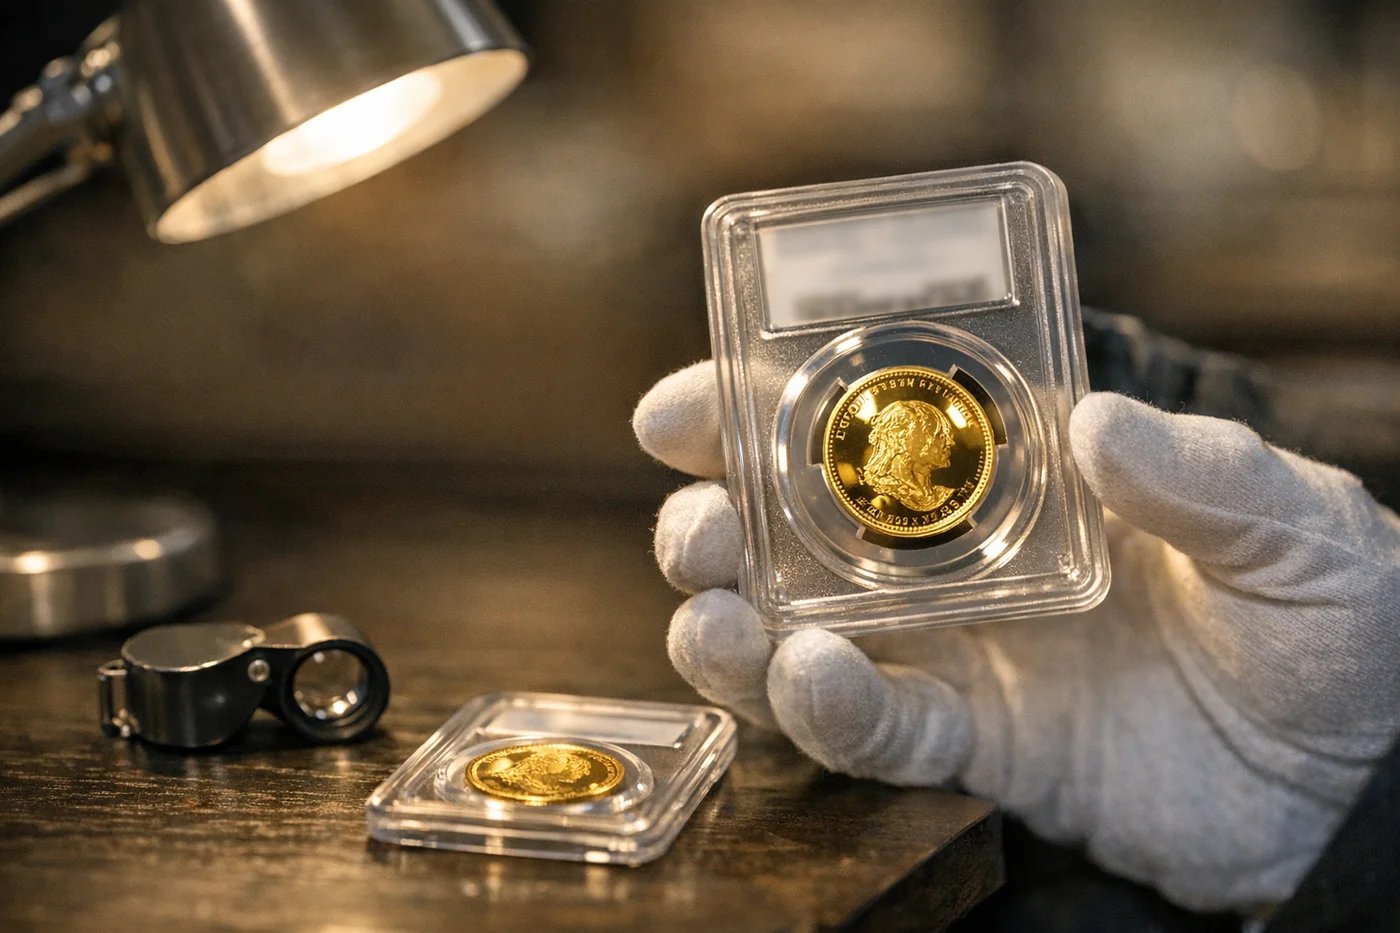
Numismatic coins can raise additional issues. A coin that is not treated as currency may fall within chattel rules, which include special provisions for certain personal possessions and sets.
A group of coins may also be treated as one set rather than as separate items. This can affect the analysis of a disposal. Rare dates, proof coins, graded coins and historic pieces may sell for more than their metal value. Keep evidence for any collector premium, including:
- Date and mint mark.
- Condition or grade.
- Proof status.
- Mintage information.
- Provenance.
- Comparable specialist sales.
- Auction or dealer records.
Seek advice from Bullion House before disposing of a valuable collection or a mixed holding.
2026 CGT thresholds and examples
For the 2026/27 tax year, the annual exempt amount is £3,000 for individuals and personal representatives, and £1,500 for most trustees. Individual CGT rates are 18% and 24%, depending on how much of the gain falls within the basic-rate band.
The following examples are illustrations only; they do not account for every possible relief, loss, ownership structure or reporting obligation.
Example one: qualifying Britannia
You buy qualifying gold Britannias for £18,000 and later sell them for £24,000.
The calculation is:
- Sale proceeds: £24,000.
- Less purchase cost: £18,000.
- Gain: £6,000.
- Less 2026/27 annual exempt amount: £3,000.
- Taxable gain: £3,000.
If the whole taxable gain falls within your available basic-rate band, CGT at 18% would be £540. However, if the coins qualify for the sterling-currency treatment described by HMRC, the disposal may be exempt instead.
Example two: a qualifying gold bar
You buy a qualifying investment-gold bar for £18,000 and later sell it for £24,000.
The calculation before allowable costs and losses is:
- Sale proceeds: £24,000.
- Less purchase cost: £18,000.
- Gain: £6,000.
- Less 2026/27 annual exempt amount: £3,000.
- Taxable gain: £3,000.
At 18%, the illustrative CGT would be £540. At 24%, it would be £720. The bar may have been VAT-exempt at purchase, but since it is not sterling currency, it is not CGT-exempt.
Example three: a Krugerrand holding
You buy qualifying Krugerrands for £30,000 and sell them for £38,000. Before allowable costs and losses:
- Sale proceeds: £38,000.
- Less purchase cost: £30,000.
- Gain: £8,000.
- Less annual exempt amount: £3,000.
- Taxable gain: £5,000.
At 18%, the illustrative CGT would be £900. At 24%, it would be £1,200. However, HMRC's example of Krugerrands as chargeable foreign currency means you should not treat them as sterling CGT-free gold UK coins.
Example four: a loss
You buy a chargeable gold bar for £25,000 and sell it for £22,000. The resulting £3,000 loss is not a gain on which CGT is payable.
Losses can interact with other gains and current reporting rules. Keep the purchase invoice, sale record and evidence of allowable costs. Bullion House recommends that you consider professional advice before using losses in a wider tax calculation.
Allowances, records and calculations
Even where no CGT is due, retain all evidence related to your gold purchase. You may later need to explain the product, acquisition cost or disposal calculation to HMRC, an accountant or an executor.
We advise you to keep:
- The purchase invoice.
- The seller's legal name and contact details.
- Purchase date and payment evidence.
- Product description and quantity.
- Coin denomination, year, fineness and fine-gold content.
- Bar refiner, weight, fineness and serial number.
- Delivery and insurance records.
- Selling invoice or dealer quote.
- Auction, dealer and transaction fees.
- Evidence supporting any collector premium.
- Records of gifts, inheritances or transfers.
Business, company, trust and estate holdings can follow different rules. Individuals should not automatically apply their personal annual exempt amount to a company or trust. Seek advice where your activity is frequent, organised or connected with a trade.
What happens when you sell a mixed gold holding?
A mixed holding can contain assets with different tax treatment. For example, you might own:
- qualifying Gold Sovereigns;
- Gold Britannias;
- gold bars;
- foreign bullion coins; and
- collector or numismatic pieces.
We suggest that you do not treat the whole holding as one tax category when you decide to sell gold. Instead, separate the items in your records and ask the buyer to itemise the quantities and prices where possible. A single mixed-lot figure can make it more difficult to match individual assets with their acquisition costs and eventual disposal values.
The same principle applies when you inherit or receive gold as a gift. Different valuation and ownership rules can apply, so a valuable or complicated transaction may warrant professional advice.
Choose gold for more than its tax treatment
CGT treatment can be an important part of choosing physical gold, but it should not be the only consideration.
Compare:
- Fine-gold content.
- Purchase premium.
- Buying and selling spread.
- Unit size.
- Recognisability.
- Condition.
- Storage requirements.
- Likely resale route.
A CGT-exempt coin can have a higher premium than a comparable gold bar. That does not automatically make one format more suitable than the other. The relevant question is how the product's costs and tax treatment fit your circumstances.
What should you check before buying CGT-free gold in the UK?
Before relying on the CGT treatment of a particular coin, check the exact asset rather than relying on a general product description.
Confirm:
- The coin's identity: Establish the exact series, denomination and issuer.
- The date: Date can be important for Sovereigns and other historic issues.
- Legal-tender status: Confirm that the relevant sterling-currency rule applies.
- The gold specification: Check weight, fineness and fine-gold content.
- The purchase records: Keep the invoice and proof of payment.
- The disposal records: Keep the eventual sale documentation.
- The current tax rules: Use the rules applicable to the tax year of the disposal.
HMRC's Capital Gains Manual and its investment-gold VAT guidance provide the relevant tax framework. Its guidance and recognised coin lists can change, so check the rules that apply when making a significant purchase or disposal.
At Bullion House, we can help you identify the physical gold you are buying or selling and explain the product characteristics. We cannot determine your personal tax liability, so seek professional tax advice where your circumstances require it.
Speak to Bullion House about your gold
If you are comparing CGT-free gold in the UK or want to understand the characteristics of gold you already own, Bullion House can help you identify the coins and bars in your holding and explain their bullion specifications.
You can visit us at:
Whether you are considering Sovereigns, Britannias, bars or a mixed holding, we can discuss the gold itself, its specification and the practical process of buying or selling. For questions about your personal CGT liability, we recommend speaking to a qualified tax adviser.
Talk to us about CGT-free gold
Visit the Baker Street showroom or contact the team to discuss the coins and bars in your holding.
Frequently asked questions
Is all gold tax-free in the UK?
Not all gold is tax-free. VAT and Capital Gains Tax use separate rules. Qualifying investment gold can be exempt from VAT, while certain sterling legal-tender gold coins can receive the CGT exemption. Gold bars and many foreign bullion coins can remain chargeable assets for Capital Gains Tax.
Which gold coins are CGT-free in the UK?
HMRC identifies Sovereigns minted in 1837 and later and gold Britannias as sterling currency. Other UK legal-tender coins may require separate verification. Check the exact issue, denomination, issuer and current guidance before relying on an exemption.
Are gold Sovereigns exempt from CGT?
Sovereigns minted from 1837 onwards are identified by HMRC as sterling currency and receive the relevant CGT exemption. Earlier Sovereigns require separate consideration, so you should not automatically apply the same treatment to every historic Sovereign.
Are gold Britannias exempt from CGT?
Yes, Gold Britannias are treated as sterling currency under the relevant HMRC guidance and receive the sterling-currency CGT exemption. This treatment comes from their legal status, not simply from being British gold coins.
Are gold bars exempt from Capital Gains Tax?
No, gold bars are not sterling currency, so they do not receive the sterling-currency CGT exemption. A gain on the disposal of a gold bar can therefore be chargeable, subject to the annual exempt amount, allowable losses, costs and the owner's circumstances.
Are Krugerrands exempt from Capital Gains Tax?
Krugerrands do not receive the same sterling-currency exemption as qualifying British coins. HMRC uses the Krugerrand as an example of a foreign currency that is a chargeable asset. You should also check other foreign bullion coins individually, rather than assuming they have the same treatment as Britannias or Sovereigns.
Next practical step
Sources and further reading
Rules and market terms can change. Check the dated sources below and take advice on tax, regulation or personal finances where your position calls for it. For the practical side of buying or selling physical gold, speak to the Bullion House team.
View 14 sources
- HMRC: Gold and VAT Notice 701/21
- HMRC: Investment gold coins and VAT Notice 701/21A
- HMRC: Capital Gains Manual on currency
- HMRC: Capital Gains Manual on chargeable assets
- HMRC: Capital Gains Manual on chattels
- HMRC: Capital Gains Manual on sets
- UK legislation: Taxation of Chargeable Gains Act, section 21
- UK legislation: Taxation of Chargeable Gains Act, section 262
- GOV.UK: Capital Gains Tax
- GOV.UK: Work out a taxable gain
- GOV.UK: Capital Gains Tax rates and allowances
- The Royal Mint: Bullion and VAT
- The Royal Mint: Tax benefits of gold investment
- The Royal Mint: Bullion investing jargon
Related guides
Use these to check the next part of your decision.
- Sovereign Coins
Britannia Coins Guide: Gold, Silver, Specifications And Tax
A source-led guide to gold, silver and platinum Britannia specifications, dates, sizes, tax, security features, premiums, storage and resale.
Read guide - Guide
What Is a Sovereign Coin? History, Gold and Value
Understand the Gold Sovereign's history, exact formats, 22-carat specification, bullion and proof finishes, rarity, tax, authenticity and resale value.
Read guide