How to Buy Gold
Gold IRA UK Equivalent (SIPP)
The closest UK equivalent of a Gold IRA is a SIPP that can hold eligible physical gold. Here is how a gold SIPP works, what qualifies and what to ask your pension provider.
At a glance
What is the UK equivalent of a Gold IRA?
The closest UK equivalent of a Gold IRA is a Self-Invested Personal Pension. Where the scheme permits it, a SIPP can hold eligible investment-grade gold, bought and held through the pension rather than owned personally. The metal stays with an approved custodian, so you cannot normally keep it at home. Eligibility depends on the product, the relevant HMRC requirements and the rules of your chosen SIPP provider, so confirm acceptance, custody and charges in writing before you buy.
- A SIPP is the closest UK equivalent of a US Gold IRA, but the rules on eligible assets, custody and access are different.
- The pension owns the gold and you own the pension benefits, so the metal stays with an approved custodian rather than at home.
- Eligibility depends on purity, form, marketability and the individual SIPP provider's rules, not purity alone.
- Collectable, commemorative and graded coins may not qualify, even when the gold content is high.
- Set-up, dealing, custody, insurance and exit charges can materially affect long-term returns, so compare the full fee schedule.
- Bullion House can supply and explain the gold. Your SIPP provider and regulated adviser confirm suitability and eligibility.
Written by
Richard Lyttle leads Bullion House across product standards, customer experience, and educational review. He reviews high-trust buying guidance so customers can understand physical gold, tax-sensitive product features, and resale considerations before they buy.
Reviewed by Richard Lyttle on 1 Oct 2026
On this page
If you are looking for the UK equivalent of a Gold IRA, the closest comparison is usually a Self-Invested Personal Pension (SIPP) that allows you to hold eligible gold-related investments within the pension wrapper.
A gold SIPP UK arrangement can give you exposure to gold while keeping the investment inside a UK pension structure. However, a SIPP is not simply a UK version of a US Gold IRA. The HMRC rules governing pension investments, eligible assets, administration, custody and access are different.
At Bullion House, we help you understand the difference between owning gold personally and holding eligible gold through a pension structure. If you are considering gold as part of a SIPP, you should establish whether the specific gold product and pension arrangement meet the relevant requirements.
What is the UK equivalent of a Gold IRA?
The closest UK equivalent to a US Gold IRA is a Self-Invested Personal Pension, commonly called a SIPP. A gold SIPP UK arrangement gives you more control over your pension investments than a standard workplace or personal pension. Depending on the scheme's rules and the provider's investment options, it may allow exposure to approved physical gold.
Bullion House can help you explore eligible gold products, but we do not operate a SIPP or provide regulated financial advice. You should confirm the structure, charges and suitability of any pension arrangement with the SIPP provider and an appropriately authorised financial adviser.
How a gold SIPP works
A gold SIPP in the UK allows your pension to gain exposure to physical gold without you personally taking possession of it. You usually open or transfer into a SIPP, make contributions or move funds from another pension, and then instruct the provider to purchase eligible gold.
The gold must remain under the control of the pension arrangement. This means you cannot normally store it at home, keep it in a personal safe or take it away for private use. An approved custodian or vaulting provider holds the metal until the pension sells it or you begin taking benefits.
The process usually follows these steps:
- You choose a SIPP provider that permits physical gold.
- You check which gold products and storage arrangements the provider accepts.
- You contribute to the SIPP or transfer funds from another pension.
- You instruct the SIPP provider to purchase eligible gold.
- The provider arranges the purchase and custody of the metal.
- You monitor the investment through the SIPP's reporting system.
- When permitted under pension rules, you sell the gold or take pension benefits.
A gold SIPP UK investment therefore differs from buying gold coins or bars for personal ownership. The pension owns the asset, while you own the pension benefits.
What gold is eligible for a SIPP?
Not every gold coin or bar automatically qualifies for inclusion in a SIPP. The product must meet the relevant pension and tax requirements, and the SIPP provider must agree to accept it.
In broad terms, SIPP-eligible gold normally needs to meet requirements relating to:
- Purity or fineness
- Recognised investment status
- Form and weight
- Marketability and reliable valuation
- Secure custody and insurance
- The rules applied by the chosen SIPP provider
Investment-grade gold bars are often considered because they provide a clearly defined weight and purity. Purity is an important part of the assessment, but it does not guarantee that a product is SIPP-eligible. Your provider must also approve the product and its custody arrangements.
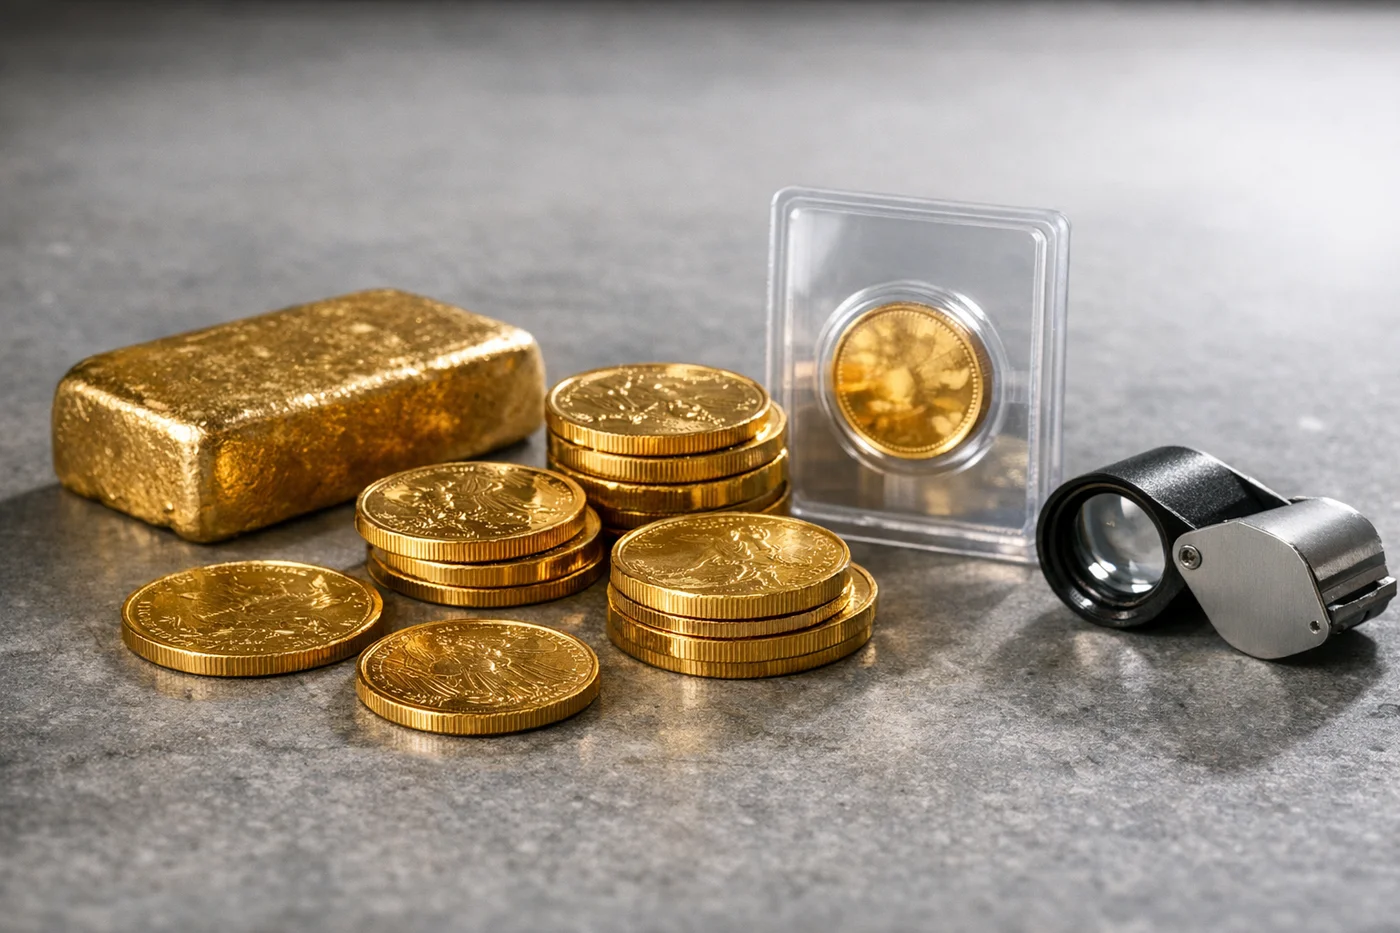
Certain recognised bullion coins may also qualify, provided they meet the relevant requirements and the provider accepts them.
Collectable, commemorative or numismatic coins may not qualify simply because they contain gold. A coin can have a high gold content but still fall outside the investment products accepted by a SIPP. Graded coins can also require particular care because their value may reflect rarity, condition and collector demand as well as their metal content.
Before you buy, ask the SIPP provider to confirm the exact product, specification and storage arrangement it accepts. Don't assume a product qualifies because another pension provider accepts a similar item.
How HMRC rules affect gold held through a SIPP
HMRC's investment-gold rules are relevant when assessing physical gold, but they are only one part of the picture when you are considering a pension.
For ordinary purchases, HMRC exempts qualifying investment gold from VAT. Gold bars and wafers must meet the relevant purity and accepted-weight requirements, while coins have their own criteria.
A gold SIPP UK investment also sits within a pension wrapper, so you need to separate the tax treatment of the gold itself from the tax treatment of the pension. This is an important distinction.
Gold bars or gold coins for a SIPP?
If your SIPP permits physical gold, the choice between bars and coins comes down to what investment the provider allows, as well as practical considerations such as weight, premium, and resale.
Can you hold gold coins in a SIPP?
You may be able to hold certain gold coins in a SIPP, but acceptance depends on the product and the provider. The coin usually needs to satisfy the relevant criteria for investment gold and fit the SIPP's custody and valuation process.
The provider may ask for information such as:
- The coin's weight
- Its fineness
- The issuing mint
- Its market value
- Its purchase documentation
- The proposed storage and insurance arrangements
Some coins carry a face value in addition to their gold content. That feature does not, by itself, determine whether the coin qualifies. The provider must assess the product under its own rules and the requirements that apply to the pension.
You should also distinguish between bullion value and collector value. A standard investment coin may be easier for a provider to value and trade than a rare or highly specialised numismatic coin. We recommend that you always obtain written confirmation before purchasing.
Browse gold coins
See the bullion coins currently available from Bullion House, including Sovereigns and Britannias.
Can you hold gold bars in a SIPP?
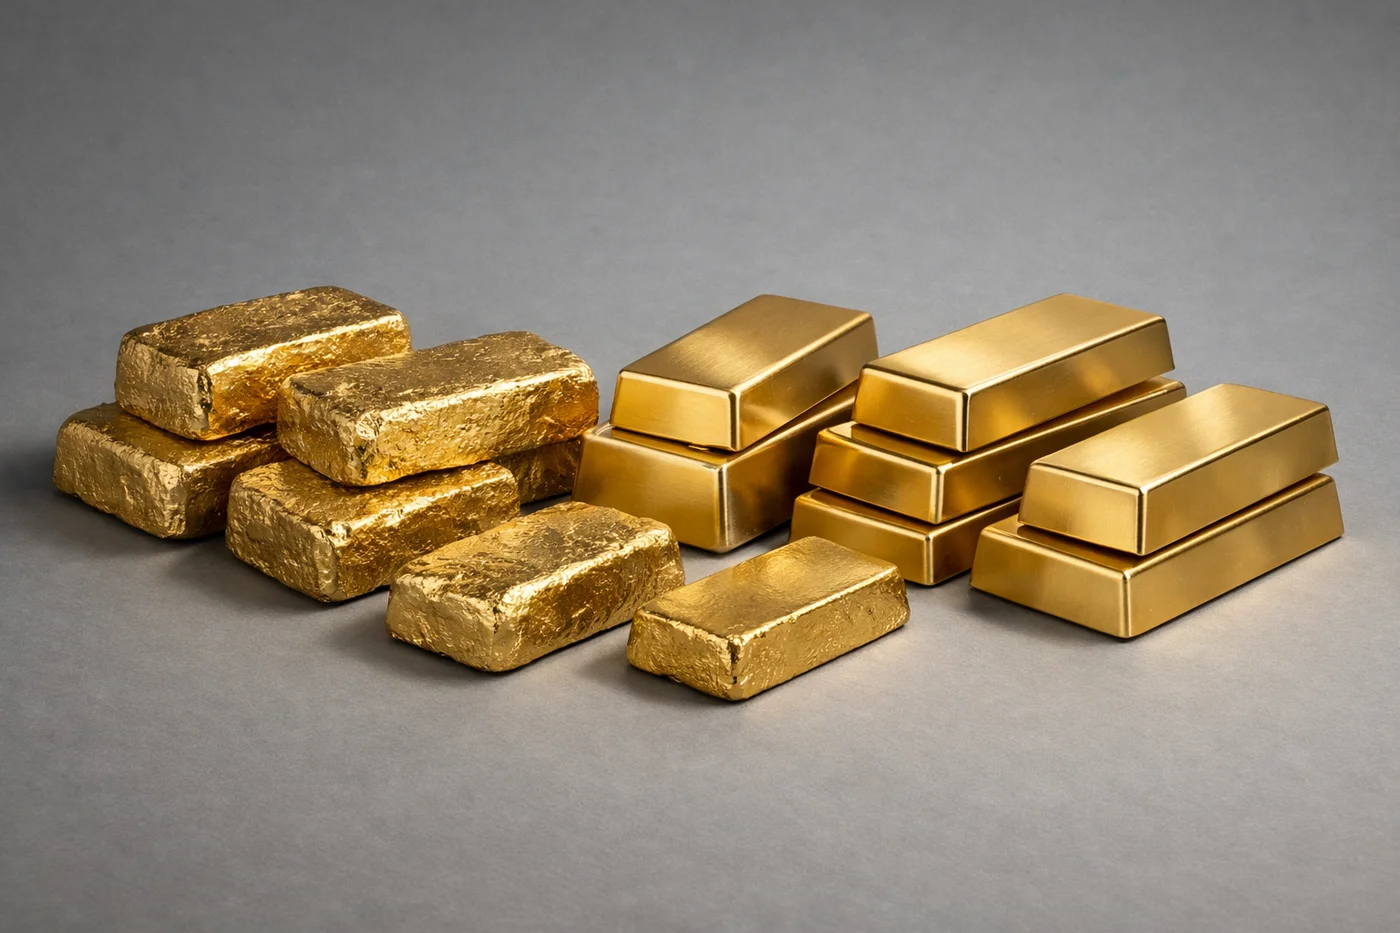
Some gold bars may qualify for a SIPP if they meet the required purity, weight and documentation standards. The provider may also require the bars to come from an approved source and remain in an approved vault.
Bars can offer practical exposure to the gold price because their value generally relates closely to their weight and purity. Larger bars may have lower premiums per gram, although they can be less flexible to sell in small portions. Smaller bars may provide greater dealing flexibility but can carry a higher premium relative to their metal content.
The right format depends on the SIPP provider, your investment objectives, the amount invested and the costs associated with buying, storing and selling the metal.
Browse gold bars
Compare investment-grade bar sizes, premiums and availability.
What about holding graded gold coins in a SIPP?
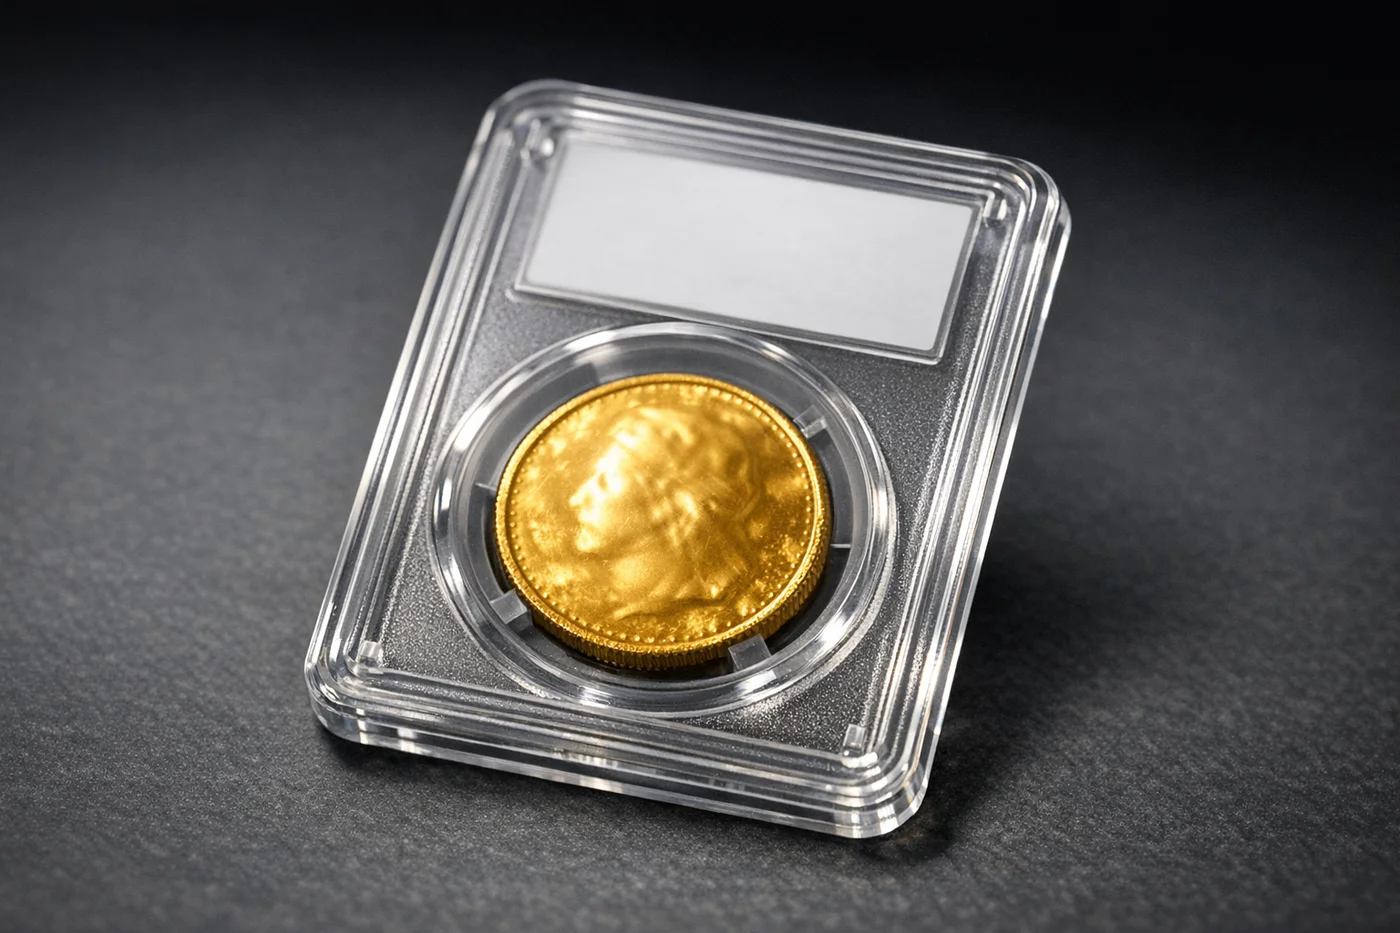
Graded gold coins receive an assessment from a grading company for factors such as authenticity, condition and preservation. A graded coin may appeal to collectors, but grading does not automatically make it suitable for a pension.
A SIPP provider may prefer products with a transparent and readily established market value. If a coin's price includes a significant collector premium, the provider may need additional information to value or sell it. Some providers may accept such products, while others may restrict their permitted investments to more conventional bullion.
Bullion House buys and sells graded PCGS and NGC coins, as well as other forms of gold. However, you should confirm with your SIPP provider whether it accepts graded coins before asking us about a purchase.
Browse graded coins
View PCGS and NGC graded gold currently held at Bullion House.
How to buy gold for a SIPP
Start with the pension provider, not the product. Ask the provider which forms of gold it accepts, who must arrange the purchase, where it will be stored and which costs apply.
Steps to take once you understand the requirements
Work through these points with your SIPP provider before you place an order.
- Confirm the provider accepts physical gold.
- Confirm the exact product and specifications.
- Check whether you can nominate your bullion dealer.
- Understand all purchase, storage and selling costs.
- Keep your purchase and custody documentation.
You can browse our current gold products to understand the types of investment gold available from Bullion House. Because availability and pricing change, the products shown on our website should not be treated as a permanent SIPP-approved list.
If you are buying gold personally rather than through a pension, you can also buy gold from Bullion House. For a gold SIPP UK purchase, however, the pension provider must approve the transaction and custody arrangements.

How is SIPP gold stored?
A suitable storage arrangement should address physical security, insurance, ownership records, allocation, valuation, audit and the process for selling or transferring the gold.
Ask whether the gold is allocated to your pension or held within a pooled arrangement. You should also enquire what happens if the custodian or SIPP provider changes, and find out how quickly you can sell the holding.
Storage and administration fees can materially affect long-term returns. Compare all charges rather than focusing only on the purchase price. Costs may include dealing fees, account fees, custody charges, insurance, valuation fees, delivery charges and selling spreads.
Which providers offer gold SIPPs?
Different SIPP providers offer different investment choices. Some may support physical gold, while others may limit investments to funds, shares, exchange-traded products or other assets.
When comparing providers, ask:
- Does the provider accept physical gold?
- Which coins and bars qualify?
- Does the provider maintain an approved-dealer list?
- Who arranges the purchase?
- Which custodian stores the metal?
- Is the gold allocated or pooled?
- What are the initial and ongoing charges?
- How does the provider value the holding?
- How do you sell the gold?
- What reporting will you receive?
- What happens if you transfer to another pension?
A provider that accepts gold in principle may still reject a particular product. Obtain confirmation before placing an order.
Bullion House can supply information about available gold products and discuss purchase options. We cannot choose a SIPP provider for you or confirm that a product qualifies for every scheme.
What are the costs of holding gold in a SIPP?
The cost of gold is only one part of the calculation. With physical bullion, you may encounter a purchase premium above the underlying value of the fine gold. You may also need to consider custody, insurance, administration and selling costs.
A SIPP can introduce another layer of fees because you are using a pension structure. Depending on the arrangement, charges may apply for:
- Setting up the SIPP
- Administration
- Buying and selling investments
- Holding or storing physical assets
- Custody
- Transferring the pension
- Closing or withdrawing from the arrangement
Always ask for the complete fee structure before committing funds.
At Bullion House, our transparent pricing guidance recommends comparing the full purchase price with the underlying fine-gold value rather than looking only at the quoted gold price.
The same discipline is useful when assessing a pension investment. Always look at the total cost of ownership.
The benefits of holding gold in a SIPP
A gold SIPP may appeal to you if you want your pension to include physical precious metals within a regulated pension framework. Potential benefits include:
- Exposure to physical gold rather than only a gold-related financial product.
- Greater control over pension investment choices.
- Diversification away from assets that may respond differently to economic conditions.
- Professional storage instead of home storage.
- A pension structure that may provide tax advantages, subject to the rules and your circumstances.
- The ability to hold eligible gold for the long term.
The risks of a gold SIPP
A gold SIPP UK arrangement does not remove the investment risks associated with gold; the gold price can fall. Currency movements can affect the sterling value of gold because international gold prices are commonly quoted in US dollars. This means transaction costs and resale spreads can also reduce your return.
There are additional considerations when physical gold is held through a pension. You need to understand:
- The pension provider
- The bullion dealer
- The custodian
- The storage arrangement
- The fees
- The legal ownership structure
- The process for selling the gold
A professional-looking website does not by itself establish how an investment works. For any regulated pension service, check the provider and the exact service it offers. A firm's regulated status does not automatically mean every product associated with that firm has the same regulatory treatment or protection.
Can you take gold out of a SIPP?
A SIPP is a pension arrangement, so withdrawals and benefits are subject to pension rules. The treatment of the underlying asset and the rules governing pension access are separate questions. Therefore, you should not assume that you can simply request delivery of the gold whenever you choose.
If your goal is to own physical gold personally, buying bullion directly is a different arrangement from holding gold through a pension. Before committing money to a gold SIPP UK strategy, ask the provider how the gold can ultimately be sold, how the proceeds are paid and what happens when you become entitled to take pension benefits. Always ensure you understand the exit route before you invest.
How Bullion House can help with physical gold
Bullion House specialises in physical gold and other precious metals, and we can help you understand the bullion itself. Our team can discuss factors such as weight, purity, fine-gold content, pricing and resale. We can also explain the practical differences between gold bars and coins.
What we cannot do is determine whether a particular pension arrangement is suitable for you or guarantee that your SIPP provider will accept a particular product. That decision belongs with your pension provider and, where appropriate, your regulated financial or tax adviser.
If you are comparing a SIPP with direct ownership, keep the distinction clear:
- Direct ownership: you buy and own the physical gold yourself.
- SIPP ownership: the investment sits within a pension arrangement and must comply with the rules and administration of that arrangement.
The two routes can offer ways to invest in gold in the UK, but they are not interchangeable.
Buy gold for your long-term plans
A gold SIPP UK investment requires coordination between you, the SIPP provider, the custodian and the bullion dealer. Start by confirming the rules and approved products with your provider, then request clear information about pricing, availability and documentation.
Bullion House can discuss available gold products and help you understand the purchase process. You can visit us at:
Bullion House Showroom
111 Baker Street, London W1U 6SG, United Kingdom
Call us on 020 7117 2889 or email info@bullionhouse.com to speak with one of our team members or to make an appointment.
Discuss gold products with a specialist
We can talk through weight, purity, fine-gold content, pricing and resale. Your SIPP provider confirms eligibility and custody.
Frequently asked questions
Is a gold SIPP the same as a Gold IRA?
No. A Gold IRA is a US retirement arrangement, while a SIPP is a UK personal pension. The UK equivalent usually involves holding eligible physical gold through a SIPP provider and an approved custodian.
What is the minimum investment for a gold SIPP?
There is no single minimum that applies to every gold SIPP in the UK. The minimum may depend on the SIPP provider, the dealer, the product size and the storage arrangement. Ask for the full fee schedule before investing.
Can I keep SIPP gold at home?
Generally, gold held through a SIPP must remain within the pension's approved custody arrangements. Taking it home could undermine the structure and create tax or compliance issues.
Is gold in a SIPP tax-free?
A pension wrapper has its own tax treatment, but this does not mean the underlying gold is simply tax-free. Investment-gold VAT rules and pension tax rules address different aspects of the transaction. Confirm the treatment of the specific arrangement with your pension provider or tax adviser.
Can I put a gold bar I already own into a SIPP?
You should not assume that you can transfer personally owned gold into a SIPP. The provider must confirm whether it accepts the proposed asset and how any purchase, transfer, valuation and custody would work.
Is a gold SIPP a good investment?
No single answer applies to every investor. Gold can diversify exposure to other assets, but its price can fall and it produces no income. A SIPP also introduces pension-provider, custody and administration considerations. Consider your objectives, costs, investment timeframe and risk tolerance, and seek regulated financial advice where appropriate.
Next practical step
Sources and further reading
Rules and market terms can change. Check the dated sources below and take advice on tax, regulation or personal finances where your position calls for it. For the practical side of buying or selling physical gold, speak to the Bullion House team.
View 13 sources
- HMRC PTM125100: tangible moveable property and investment grade gold bullion
- HMRC PTM121000: pension scheme investments, essential principles
- Exception of Tangible Moveable Property Order 2006, article 2
- HMRC: Gold acquisitions, imports, investments and VAT (Notice 701/21)
- HMRC: Investment gold coins (VAT Notice 701/21A)
- MoneyHelper: SIPPs explained, self-invested personal pensions
- GOV.UK: Personal pensions, your rights and provider checks
- GOV.UK: Claim tax relief on your private pension payments
- FCA FG13/08: a guide for SIPP operators
- FCA Firm Checker: verify a regulated pension provider
- LBMA precious metal prices and benchmarks
- PCGS certificate verification
- NGC certification verification
Related guides
Use these to check the next part of your decision.
- How to Buy Gold
Gold 101: A Beginner’s Guide to Physical Gold
Learn how physical gold ownership, coins, bars, pricing, UK tax, storage and resale work before you make a first purchase.
Read guide - Gold and UK Tax
CGT-Free Gold in the UK
A source-led UK guide to investment-gold VAT, sterling legal-tender coins, Capital Gains Tax, non-exempt gold, records and disposal planning.
Read guide